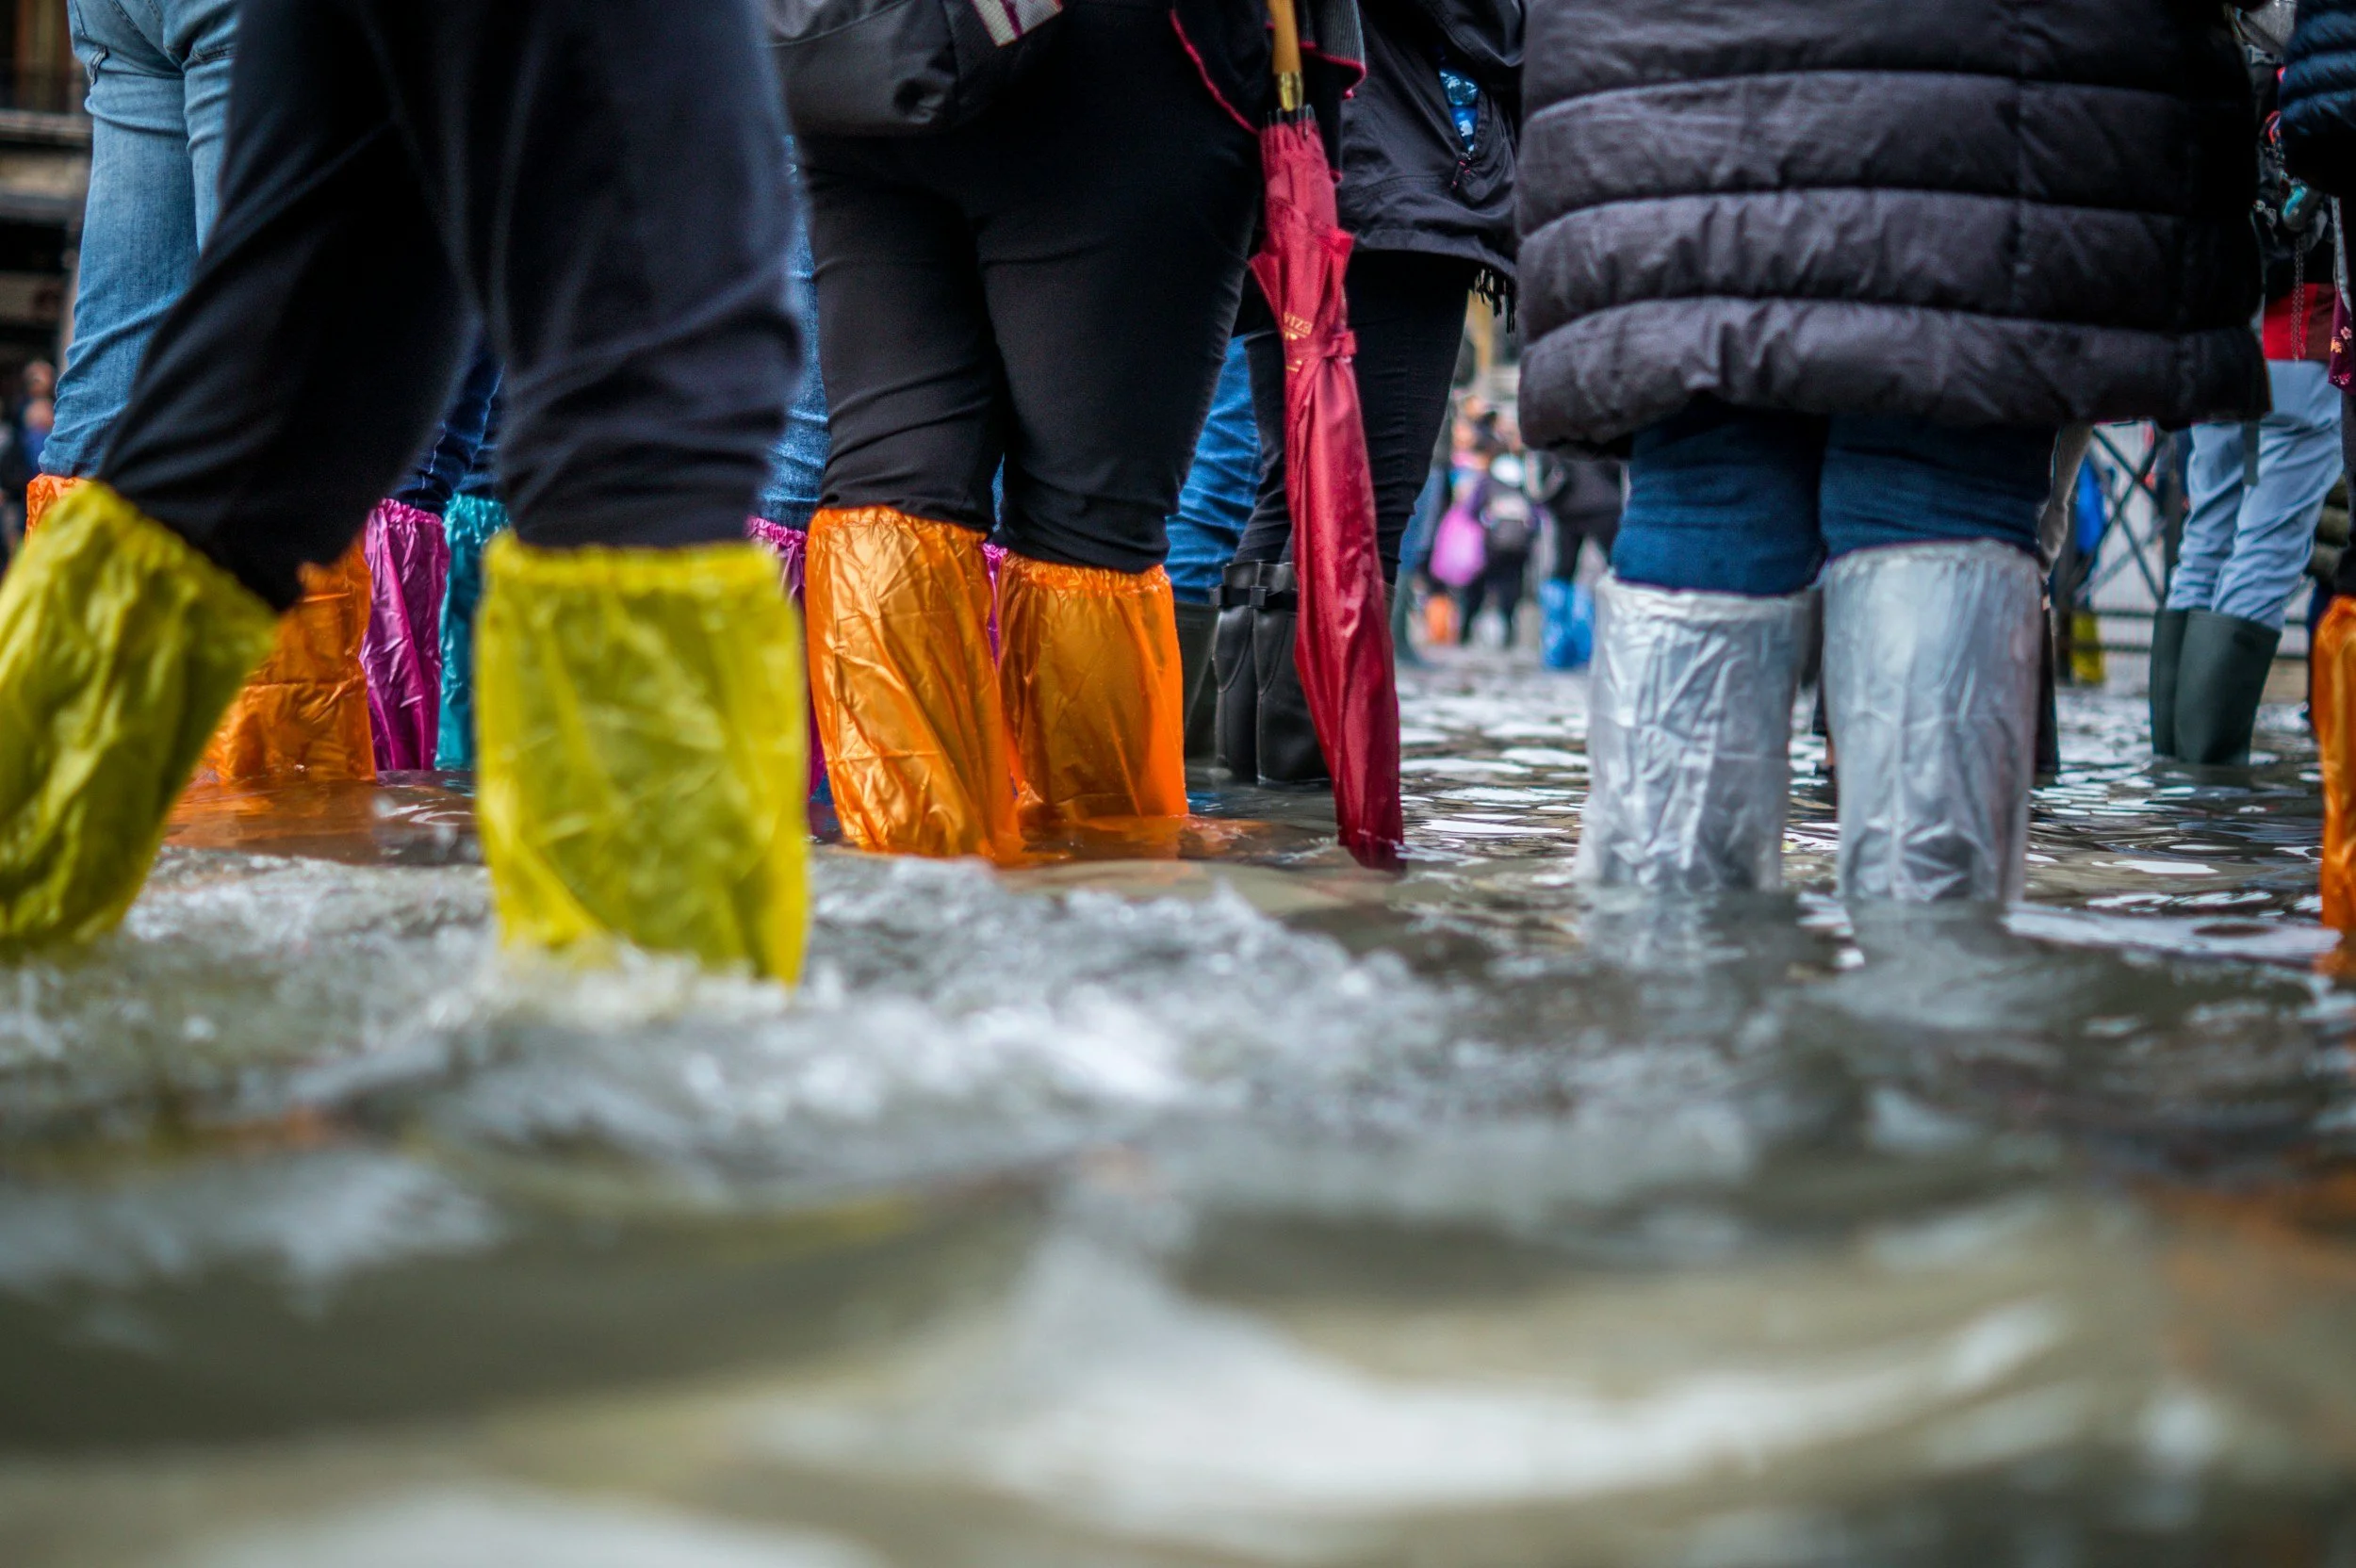
It seems like every week brings a new disaster tied to extreme weather, whether it's the catastrophic flooding that devastated communities across the Himalayas, Hurricane Lowell drowning Kauai and knocking out power to most of the island, Tropical Storm Marie lashing the Southern California coast at Long Beach, or the wildfire smoke from Canadian fires that choked skies across much of the Eastern US earlier this summer.
As the World Meteorological Organization warns of a very strong El Niño heading into winter, which the agency has called the most confident forecast of its kind it has ever issued, some parts of the US can expect excess moisture while other regions long accustomed to snow face warmer, drier conditions. You may be wondering whether there's anything you can do to prepare.
Does insurance pay out fast enough after a disaster?
The uncomfortable truth is that insurance reimburses, it doesn't front. After a disaster, the bills come first: the deductible, a rental while your home is unlivable, replacement essentials, and a contractor's deposit. The claim money comes later, sometimes months later, and the wait only grows when a whole region files at once.
Between a deductible of a few thousand dollars, a few weeks in a rental, and that contractor deposit, you may have to come up with well into five figures before you see a dime for a claim, even if the loss is fully covered.
For households with significant assets, the trap isn't a lack of resources. It's that those resources are often invested, requiring a sale to generate enough cash. Selling investments to cover an emergency, especially during turbulent times, might lock in a loss or trigger a capital gains bill, turning a temporary, covered setback into a permanent hit to the portfolio.
The smarter move is a genuinely accessible reserve sized to front an emergency, so a disaster never forces a bad sale or an expensive credit card balance. It also pays to know how and when your policy pays out before you rely on it.
What does your insurance actually cover?
Most people assume their homeowner’s policy has them covered. Often it doesn't, in ways that surface only at the worst time.
The biggest blind spot is flood. Standard homeowners policies exclude it: rising water, storm surge, and the overflow of a river or bay. Water damage from an internal issue, like a pipe exploding, is different. But coverage for a flood from a weather event takes a separate policy through FEMA's flood program or a private insurer, and that federal program caps building coverage at $250,000. These policies also carry a 30-day waiting period, so flood coverage isn't something you can add as a storm approaches.
Underinsurance is the next gap. Building costs have climbed sharply, and a dwelling limit set a few years ago may no longer cover today's rebuild, meaning that even a fully covered total loss can pay less than the bill. Related is the upgrade trap: insurance pays to restore what you had, not to improve it, so nicer finishes chosen during a rebuild come out of pocket.
Then there's loss of use, which pays for temporary housing while your home is repaired. Know your limit and how long it lasts before you're the one booking the rental. The same logic extends to the car: comprehensive coverage, not collision, pays for a vehicle damaged by flood, fire, or a falling tree, so understand what you have there in case you want to add coverage.
Could your insurer drop you before the next storm?
In higher-risk areas, the bigger threat is no longer a claim being denied, it's coverage being pulled. Insurers have been non-renewing policies and exiting markets as losses mount, and replacement coverage is far harder and pricier once an area has been hit or a claim filed. Checking your exposure now, rather than after a loss, is the whole game. Where the private market has retreated, the state fallback of last resort is rarely enough on its own to rebuild a high-value home. And never let a policy lapse in the shuffle, since a gap can trigger lender-placed insurance, which is costly and protects the lender rather than you.
How would you prove what you lost?
After a total loss, the burden of proof is on you. Insurers ask you to itemize what you owned, with pricing, and memory is a poor inventory. What you can't document, you generally can't collect.
Survivors of the January 2025 Eaton Fire in Altadena learned this the hardest way. Submitting a claim meant reconstructing a home's entire contents from memory, drawer by drawer, while grieving and displaced, with lists running into the thousands of lines. It was one of the most punishing parts of an already devastating loss.
A walkthrough video changes that. Take the time to walk through your home, opening drawers and closets and recording higher-value items, then be sure to store the file in the cloud, where it survives even if the house doesn't. It doesn't erase the task, but your future self would be working from footage instead of memory, sparing some of that load at the worst moment and producing a fuller claim. This is what turns the coverage you confirmed above into dollars that actually show up. For more on filing a claim, refer to this post.
What about the rest of your preparation?
The physical preparation matters too: an emergency kit, a go-bag, an evacuation plan. FEMA covers that ground well at Ready.gov. What a checklist won't tell you is whether your finances are ready, and that's the part worth reviewing before this super El Niño winter sets in.
Being prepared buys you more than a faster recovery, should you be affected by extreme weather. It buys the ability to recover on your own terms, without a forced sale or a pile of debt, and still have something left to help the people around you when they need it. In a season when disasters seem to arrive weekly, that kind of resilience is worth building before you need it.
If it's been a while since you reviewed your coverage and emergency reserves against the risks you actually face, let's take a look together.