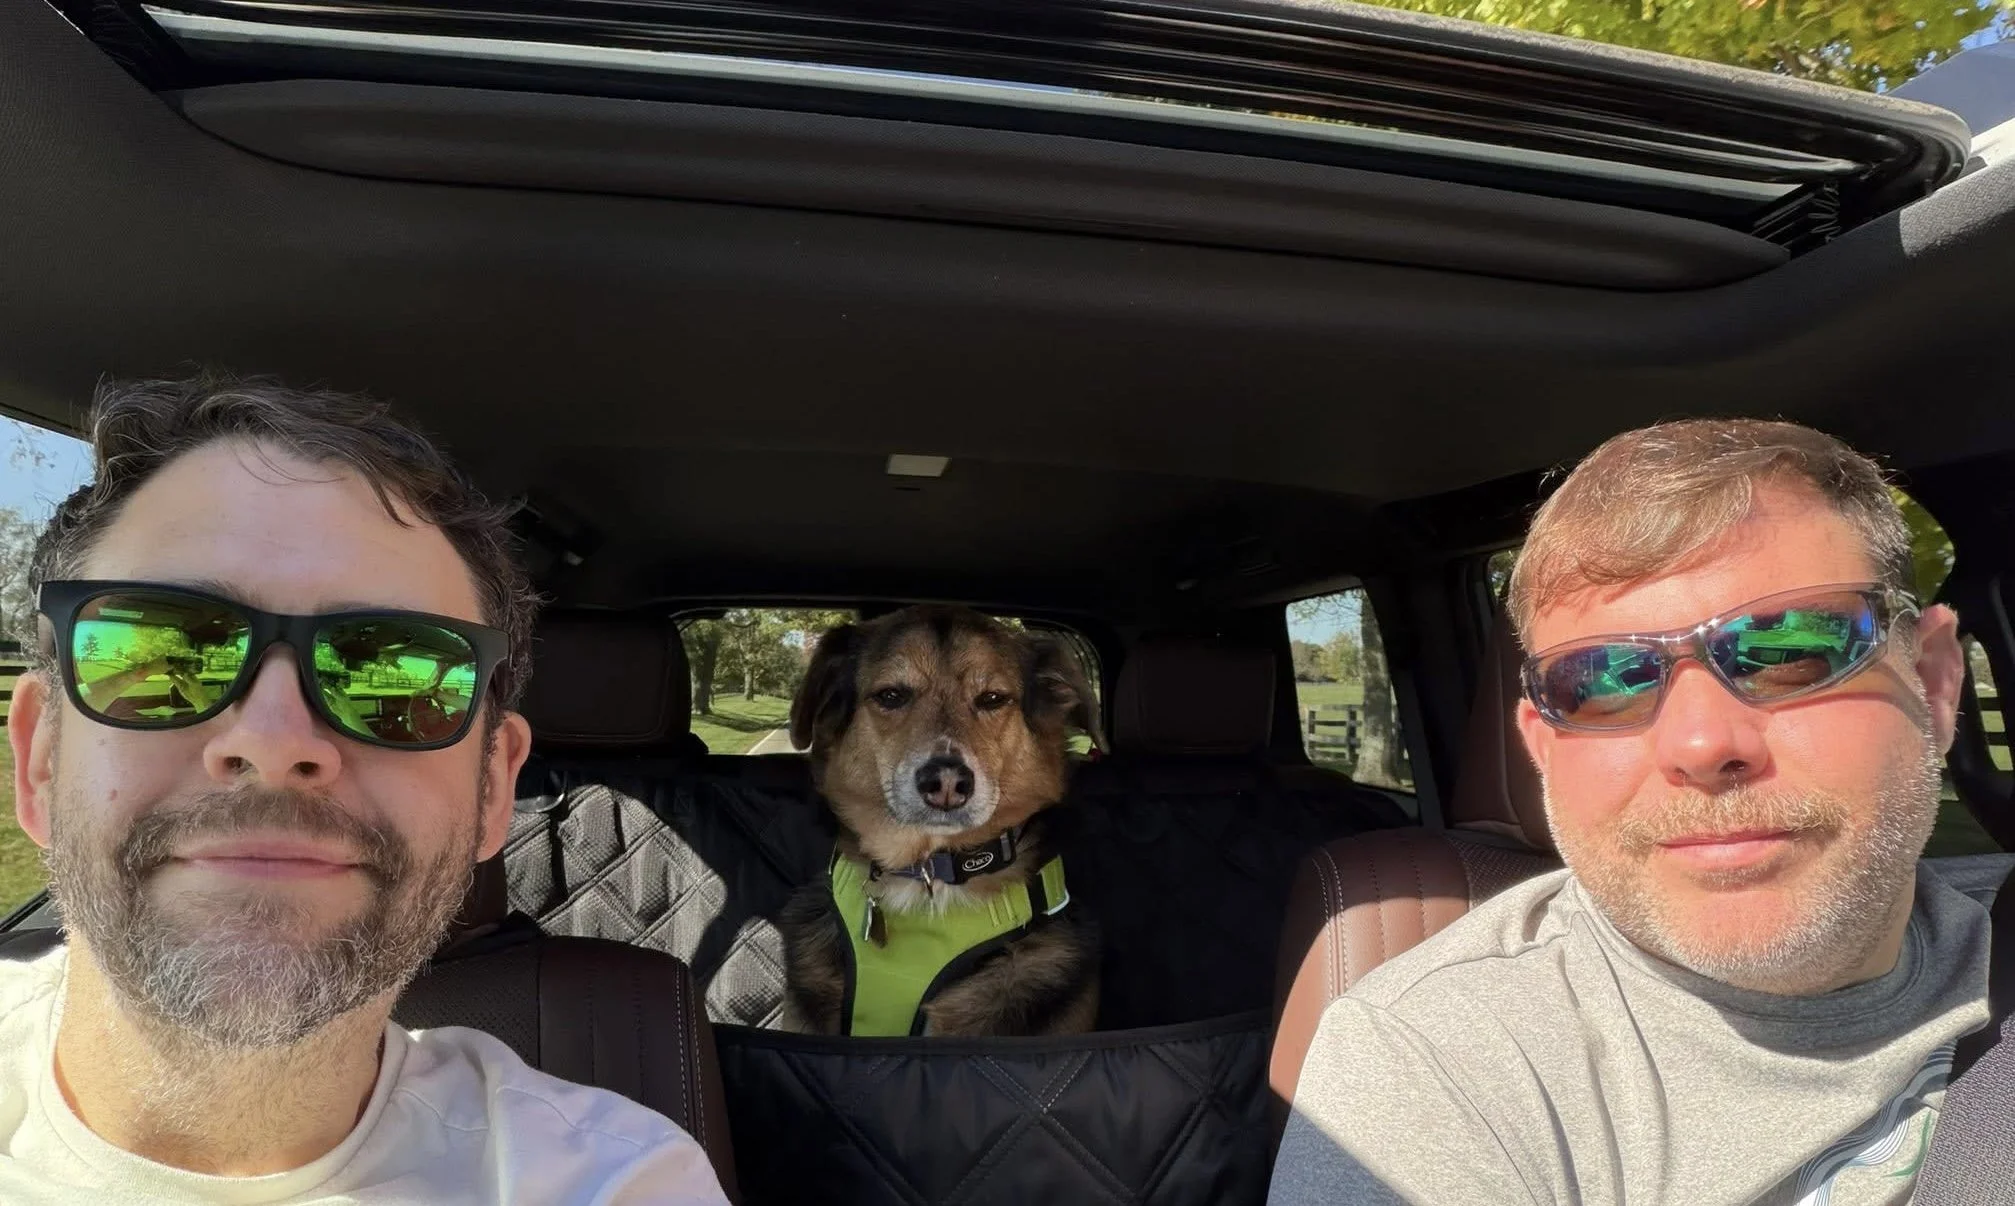
For two decades, Andy Pulsfort has spent his days at The Prosperity People getting to know our clients: their goals, their worries, their adventures, their milestones and the dreams their financial plans make possible.
After years of listening and learning, we thought it was time to turn the tables. In this Q&A, Andy shares what first drew him to finance, what a typical workday really looks like, why so much of his work has little to do with numbers and what prosperity means to him personally.
What drew you into finance as a career?
I think I was drawn to finance from a pretty young age. My father was in banking and my mother worked for a financial advisor, so money and finance were always part of the world around me. I was fascinated by money even as a kid. In fact, when I was little, I thought the solution to needing money was simply to go to “The Owl,” which was the ATM network Central Trust Bank used at the time.
The real turning point came at the University of Dayton, where I had the opportunity to be involved with what is now the Davis Center for Portfolio Management. We weren't just learning about investing in a classroom – we were investing real money from the University's endowment. Having that kind of hands-on experience and seeing investing come to life really sealed the deal for me. I knew finance was what I wanted to do.
What is the first thing you do when you get to the office?
I actually start my workday before I leave home. I review my calendar and emails so that by the time I get to the office, I already have a pretty detailed plan of action and know what I want to knock out first.
But just as important is some daily chit-chat with my coworkers. That informal interaction matters to me and is an important part of starting the day. It also gives Lisa a chance to set me straight and make sure I know what the agenda really is for the day!
What does “checking the markets” involve?
We build sustainable portfolios that are designed to serve our clients over the long term, so daily market movements are usually pretty irrelevant to the bigger picture. Markets react constantly to news and headlines, but ultimately, they tend to settle based on the economic conditions and valuations that actually matter.
If there are a lot of headlines or something interesting happening, I'll certainly check the markets throughout the day out of interest. Otherwise, I may not look closely until the end of the day. An afternoon of market movement doesn't really tell me whether a client is on track to meet their goals and live their dreams—and that's ultimately what matters to me.
What is something about your job that would surprise people who do not work in finance?
People might be surprised by how much of this job has very little to do with numbers. I've had clients jokingly refer to us as life coaches or counselors, and there is probably some truth to that.
We can't control the markets, but we can help people better understand their relationship with money. Money can be tied to all kinds of emotions – security, fear, success, independence, even guilt. Sometimes our role is helping someone recognize those things and, if they want to, change the way they think about money.
A big part of what we do is help people feel comfortable with the decisions they're making so that money becomes a tool for living their lives rather than a constant source of worry.
What is the most rewarding part of your day?
One of the most rewarding parts of my job is hearing about what our clients are actually doing with their lives – the trips and adventures they've taken, the projects they've tackled, or simply the things they've always wanted to do.
I love seeing their excitement and knowing they were able to be fully present and enjoy those experiences because they felt secure about their finances. There's also something incredibly rewarding about seeing a client retire when they planned to, without constantly worrying about whether they can afford it.
Those are the moments when you realize the financial planning itself isn't really the end goal. It's what that planning allows someone to do with their life that matters.
What is the most challenging part of your day?
One of the most challenging parts is seeing clients beat themselves up over decisions they've made in the past. It's easy to look backward and think, “I should have saved more,” “I shouldn't have spent that,” or “I should have started sooner.” But none of us gets every decision right, and the reality is that people can't do everything.
Financial planning involves tradeoffs, and the sacrifices that seem easy on paper aren't always easy in real life. Everyone has different priorities, responsibilities and experiences with money. Change can be hard, even when we know what we want to change.
Part of my job is helping clients acknowledge the past without getting stuck there, focus on the decisions they can make today, and recognize that meaningful progress doesn't require perfection.
What do people misunderstand about what a financial advisor/planner does?
I think one of the biggest misconceptions is that our job is primarily about picking investments, beating the stock market, or obsessing over financial minutiae. Those things can get a lot of attention, but they're not really the point of financial planning.
A properly diversified portfolio that includes things like fixed income isn't necessarily designed to beat the broad stock market—and judging it solely on that basis misses why it was built that way in the first place. The goal is to build a financial plan and investment strategy appropriate for that particular person's life, goals, timeline and comfort with risk.
There are certainly technical details we need to understand and get right, but our real job is helping clients make good decisions, adapt when life changes, and stay on track. Success isn't whether we beat an index this year. It's whether the client has the resources to do the things that matter to them.
What does prosperity mean to you, personally?
To me, prosperity is having the freedom and confidence to live the life that's meaningful to you. Money is certainly part of that, but I don't think prosperity is defined by a particular account balance or level of wealth.
It's being able to spend time with the people you care about, have experiences that matter to you, pursue the things that excite you, and feel secure enough about the future that you can actually enjoy the present.
After doing this for 20 years, I've seen people with very different levels of wealth live incredibly prosperous lives. I think the real goal is getting to a place where money supports the life you want to live rather than becoming the thing you're living for.
Disclosure: This article is for informational purposes only and is not investment, tax, or legal advice.